
How sustainability goals shape rebuild costs and buildings insurance

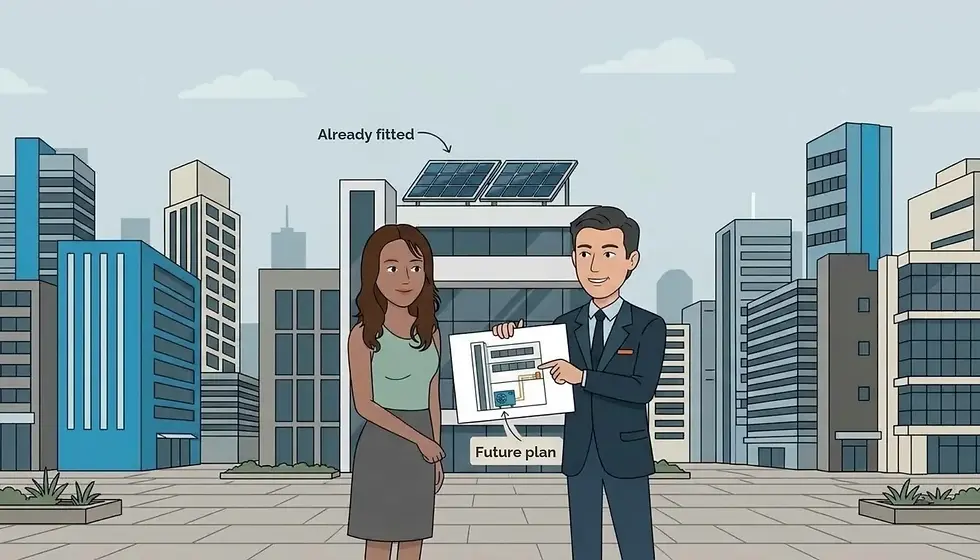
Meet Terri, an office owner who has fitted solar panels and plans to replace the building’s old heating system with one that uses less energy. At renewal, they tell their broker that, if the office ever needed rebuilding, they would want the new building to be more energy efficient.
The solar panels are already fitted, while the heating upgrade is still a plan. The broker can help Terri understand how the existing installation is treated in the assessment, then discuss the planned upgrade with the insurer. This gives each conversation a clear starting point.
What ESG means for this conversation
ESG stands for environmental, social and governance. For this article, the focus is on environmental goals and how decisions about the building are made and recorded. An owner may want to use less energy, choose different materials or reduce waste when rebuilding.
The governance part means keeping a clear record of those plans, the advice received and the actions agreed. This helps everyone understand what has been decided and what still needs an answer. A client does not need a formal ESG policy to have this conversation. A plan to improve the building is a useful starting point.
Understand what the rebuild figure covers
At RebuildCostASSESSMENT.com, we estimate what it would cost to rebuild a property if it were destroyed. We consider information about its size, construction and features. The figure also takes account of related costs, such as demolishing damaged remains and paying architects and other professionals.
The report explains what has been included and any details the surveyor has had to assume, for example where information about the building is limited. Checking these points with the client helps identify anything that needs correcting or explaining.
Where solar panels are already fitted, our rebuild estimate includes their like-for-like replacement. If they are insured separately, let us know so we can review whether they should be removed from the estimate. This helps the broker check how the assessment and insurance arrangements fit together.
A rebuild assessment takes account of the building rules and legal requirements in force when it is prepared. These can affect what would be needed when rebuilding. The surveyor can explain how those requirements have been reflected in the estimate.
The rebuild estimate considers the property as it stands, alongside current building requirements. Terri’s planned heating upgrade is a separate conversation for the broker and insurer, who can explore how the policy would respond if Terri wanted to make that improvement when rebuilding.
Wanting a greener building does not mean adding a fixed percentage to the rebuild figure. For improvements already completed, simply adding the original installation price can also be misleading. Some costs may already be included, and rebuilding costs may differ from the price originally paid.
Check what the policy will cover
The insurer needs to understand how the building is constructed and what changes are planned when deciding what cover and terms to offer. Some insurers have also developed cover to support greener rebuilding.
In June 2025, Aviva announced wider insurance options for certain large commercial buildings using timber. Changes to its corporate property cover also supported more sustainable rebuilding. It highlighted the value of early discussions with its underwriting, engineering and claims teams.
For your client, the next step is to check their own policy. Find out whether the intended improvements would be covered and whether any limits or conditions apply. Increasing the amount of buildings cover does not automatically mean an upgrade is covered. The insurer can also confirm how the rebuild estimate should be used when setting that amount.
Turn the conversation into clear actions
For Terri, start by confirming what work has been completed and what is planned. Check that the report describes the building correctly, then ask the surveyor how the existing solar panels have been treated. Take questions about cover for the proposed heating system to the insurer.
Keep a short note of what was checked, the answers received and the action agreed with the client. Where a point remains open, record who will follow it up. This helps a colleague understand the position if they pick up the file later.
While Terri’s heating upgrade is still a plan, discuss the insurance implications with the insurer. Once work is completed, ask RebuildCostASSESSMENT.com whether the assessment needs reviewing and check with the insurer whether the cover needs updating.
Get help with the rebuild figure
A client's environmental goals can prompt a useful review of their building and its insurance. The practical aim is to understand what the rebuild figure includes and confirm how the cover fits their plans.
If your client's building details or rebuild figure need attention, speak to RebuildCostASSESSMENT.com. We can explain what information is needed and discuss whether a Desktop or Site Assessment is suitable for the property.


